Avant

Screenshots
Details
- Rating
- 5.41K reviews
- Version
- 4.7.0
- Developer
- Avant, LLC
Analysis by Norviv
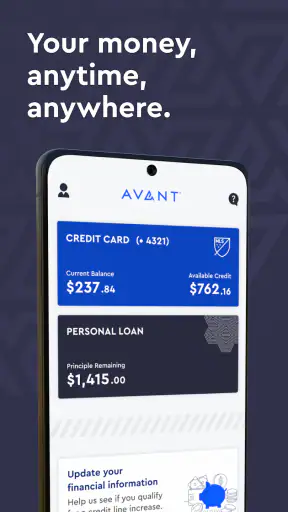
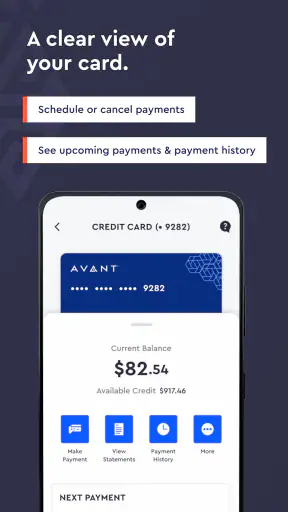
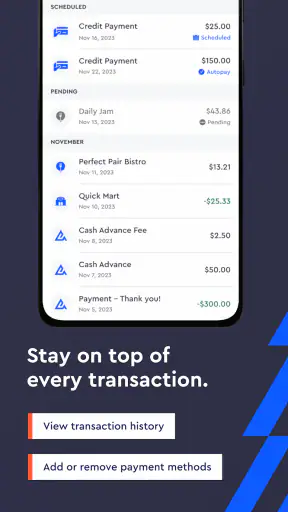
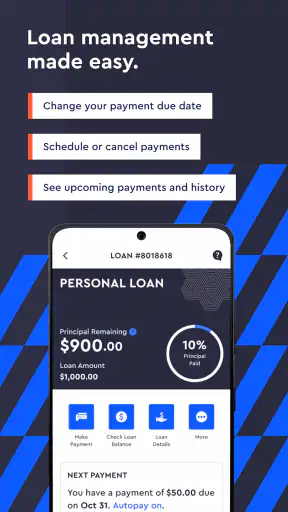
I found Avant most useful when I stopped thinking of it as a general banking app and treated it as a focused control panel for an Avant card or loan. That distinction matters. The app is built around practical account tasks: checking transactions, making a payment, and keeping an eye on the balance connected to your Avant account. In my experience, that narrow purpose makes it easier to understand than a crowded finance app, especially when I only want to confirm what is due or see whether a recent payment has appeared.
It is a free finance app from Avant, LLC, available for Android devices running Android 6.0 or later. The app is rated for Everyone, which fits its straightforward money-management role, although the financial decisions made through it are still adult responsibilities. With a 4.7 average from around 58 thousand ratings and more than 500 thousand installs, it has clearly attracted a substantial user base. I would still judge it by how well it fits a person’s account habits rather than by popularity alone.
How Avant fits into a shared household routine
A realistic household example is a couple sharing responsibility for monthly bills while keeping their financial accounts separate. One person may use Avant to review the account and submit a payment, while the other simply needs to know whether that payment has been handled. The app can support that conversation by giving the account holder a direct place to check transactions and payment activity instead of relying on memory, paper statements, or a long chain of messages.
That does not make Avant a shared household ledger. I would not use it as a replacement for a family budgeting app, a joint spreadsheet, or a full bank dashboard. Its value is more specific: it helps the person responsible for an Avant card or loan handle that account from a phone. If several people need equal access, separate financial identities, or a combined view of rent, utilities, savings, and spending, another tool will be more suitable.
For a shared-device situation, I would be careful about who opens the app and when. A phone left on a kitchen counter can become an informal window into sensitive financial information. Even when a household trusts one another, account details should not be treated like a grocery list. I recommend keeping the app on the account holder’s personal device whenever possible and avoiding casual sign-ins on a tablet used by children or guests.
The strongest shared-use benefit is coordination without unnecessary exposure. A user can check the relevant account before telling a partner that a payment was made, then close the app rather than showing every transaction. That small habit keeps the conversation focused on the task. It also avoids the common household problem of one person assuming that “I paid it” means the payment has already appeared in the account.
What I would do before handing over a phone
I would not hand the phone to another household member while Avant is open on a transaction screen. I would return to the device’s normal home screen, use the phone’s own security features, and make sure the account session is not being treated as a communal login. These are simple boundaries, but they matter more in a finance app than they do in a recipe or weather app.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
I would also decide who is actually responsible for each action. If one person owns the Avant account, that person should remain the final checker for payments and account activity. Another household member can remind them, help read a screen, or coordinate timing, but shared access should not become shared uncertainty about who submitted a payment.
This is one area where Avant’s focused design is both helpful and limiting. Because the app centers on the Avant relationship, it is easier to keep attention on that account. At the same time, it does not replace a household system for dividing responsibilities. I would write down the agreed payment date or use a separate reminder, then use Avant to verify the account task itself.
Setup boundaries that prevent avoidable confusion
My first recommendation is to install the app for the actual account holder, not simply on the device that happens to be available. The current version is 4.7.0, and the Android requirement is modest, so compatibility should not be a major obstacle for many older phones. Still, a compatible phone is not automatically the right phone. The device should be one that the account holder can secure, update, and access reliably.
During setup, I would slow down at every sign-in and verification step rather than rushing through it while distracted. Finance apps deserve a quieter setup than social apps. I would check that the account information belongs to the correct Avant relationship, confirm that I am using the intended device, and avoid saving credentials in a shared browser or a family password list that everyone can open.
A useful boundary is separating account access from household planning. Avant can show the activity connected to the card or loan, but I would not assume that it knows how the household wants to divide expenses. If a payment comes from a joint bank account, the household still needs its own agreement about who checks the bank balance, who submits the payment, and who confirms the result.
That separation prevents a subtle mistake: treating visibility as permission. Seeing an account on a phone does not mean every person using that phone should be able to act on it. I would keep the app tied to the person authorized to manage the account and use a shared calendar, note, or conversation for reminders. The app handles the account view; the household handles the agreement.
I would also avoid making a payment while connected to a device or network I do not control. This is not a criticism unique to Avant; it is a sensible rule for any financial service. If I am helping a relative, I would let them hold the phone and enter sensitive details themselves whenever practical. Assistance should reduce confusion without turning another person into the unofficial owner of the account.
Why a focused account app can be easier than a bank alternative
Compared with opening a general bank app, Avant has a narrower job. A bank app may show checking, savings, transfers, cards, alerts, and unrelated products all at once. That wider view is valuable when I am managing an entire financial life, but it can also make a simple card or loan payment feel buried. Avant is more appealing when the user wants to reach the relevant account quickly and avoid navigating through a larger financial dashboard.
The trade-off is that a bank app usually gives a broader picture of available cash and outgoing obligations. If I need to decide whether a payment will leave enough money for rent, groceries, or another bill, I may still need to open the bank app separately. Avant can help me manage the Avant account, but it should not be mistaken for a complete household cash-flow tool.
That is the first non-obvious workflow I would recommend: use two checks instead of one. Before making a payment, review the Avant account in the app, then check the funding account through the appropriate bank channel. This takes longer than pressing a single button, but it reduces the risk of managing the payment correctly while overlooking the household’s available balance.
Coordination without turning one account into a family dashboard
In a household, the best use of Avant is often a small confirmation loop. One person says the payment needs attention, the account holder opens the app, reviews the relevant information, completes the action if appropriate, and then confirms the result. I prefer this over giving several people informal access because it keeps responsibility visible.
Transaction review is especially useful in that loop. Instead of relying on a text message that says “it should be done,” the account holder can look at the app and use the displayed activity as the basis for the conversation. I would still keep receipts or confirmation details when the situation calls for them, because an app screen is not the same thing as a household record.
Another practical use is separating routine checks from urgent checks. A person might review transactions after a planned payment, while checking more promptly after noticing an unfamiliar purchase or an unexpected account change. This does not mean the app should become a source of constant anxiety. A short, consistent review habit is more useful than repeatedly opening the account without a clear question.
For couples, roommates, or adult relatives, I would agree on plain language before using the app together. “The payment was submitted” and “the payment is visible in the transaction history” are not necessarily identical statements. Defining that difference helps prevent arguments and makes it clear what each person has actually verified.
Avant is less suitable when coordination requires multiple people to edit one shared budget, assign categories, or reconcile several accounts. In that case, a budgeting service or shared spreadsheet will provide the missing household layer. I would use Avant as the source for the Avant account’s activity, not as the central place where every financial decision is documented.
A useful routine for payment days
My preferred routine is deliberately short. First, I identify the account and the task instead of opening the app casually. Next, I review the current activity so I do not duplicate a recent action. Then I check the funding account separately, complete the payment if everything looks right, and return later to verify the resulting activity. The final check is the step people often skip, yet it is the one that turns an intention into a confirmed household record.
This workflow is also helpful for someone who receives assistance from a trusted relative. The relative can help interpret the task or remind the account holder, but the account holder remains involved in the actual review. That preserves independence and reduces the chance that a well-meaning helper makes a decision without the person who owns the account understanding it.
Age context, trust, and who should use it
The Everyone content rating describes the app’s general presentation, not the age or financial readiness required to use an Avant card or loan responsibly. I would be comfortable with a teenager seeing the app in a household conversation about how payments work, but I would not treat that as a reason to give a young person account access. Financial maturity, authorization, and device security are separate questions from content rating.
For an older adult, Avant may be useful if the person wants a direct way to review transactions and manage payments without navigating a full banking ecosystem. The focused purpose can make the app less intimidating. I would still set it up slowly, keep the account holder involved, and avoid storing access details where a helper can retrieve them without permission.
Trust also has limits. A family member may be trustworthy and still be the wrong person to manage a payment because they do not know the household’s cash position, payment schedule, or account history. I would rather create a clear assistance routine than assume that closeness automatically makes shared access safe.
For users who are uncomfortable with mobile finance, the app’s narrow purpose may help, but only if they can reliably recognize the account activity and payment task. If a person needs in-person guidance for every step, the app may be a useful companion rather than a complete solution. The right choice depends on whether the user wants mobile control or simply needs reassurance from another person.
I would also skip Avant as a primary tool if my goal were investment tracking, detailed spending categories, credit education, or a unified view of multiple lenders. Its strength is account servicing for Avant products. Choosing it for a broader purpose would create extra work because I would still need other apps for the rest of the financial picture.
My household verdict after using the app
Avant makes sense for someone who already has an Avant card or loan and wants a direct mobile route to payments and transaction review. I like its focused role because it keeps the most common account tasks close at hand. The app is free, its Android support reaches older operating systems, and its strong 4.7 average suggests that many users find the experience dependable enough for regular account management.
My reservation is not that it tries to do too little; it is that users may expect it to do more than it is designed for. It is not a household budget, a shared financial workspace, or a replacement for the app belonging to the bank that supplies payment funds. The more complicated the household’s finances become, the more important it is to pair Avant with a separate planning and record-keeping method.
The best fit is an individual account holder who wants to check activity, manage a payment, and keep the Avant relationship separate from the rest of the household’s money. It can also work well in a coordinated family routine when the account holder stays in control and relatives help through reminders or discussion rather than casual access.
My practical advice is to use Avant as a verification tool, not just an action button. Check recent activity before paying, confirm the funding account elsewhere, keep device access personal, and distinguish between a submitted payment and a payment that appears in the account history. Those habits add more value than simply installing the app and tapping through the first available option.
For that specific purpose, I would recommend Avant to eligible account holders who prefer a straightforward mobile account view. I would choose a broader banking or budgeting alternative when the real need is household-wide coordination across several accounts. Used within those boundaries, Avant is a sensible, focused finance app rather than an all-in-one answer to every money question.
Frequently Asked Questions
01What is Avant, and what can I use it for?
Avant is a digital application designed to provide users with a convenient way to access its main services and features from a mobile device. Depending on the version and platform, it may include tools for managing information, exploring content, completing tasks, or interacting with connected services. Before downloading, review the official description to confirm that its current features match your needs.
02Is Avant free to download and use?
Avant may be available as a free download, but some features or services could require payment, a subscription, an account, or additional in-app purchases. Pricing and availability can vary between Android and iOS, as well as by country. We recommend checking the app-store listing carefully before installing, especially the subscription terms, renewal conditions, and cancellation policy.
03What devices and operating systems are compatible with Avant?
Compatibility depends on the specific Avant app, its current release, and the device you are using. Check the Google Play Store or Apple App Store listing for the minimum Android or iOS version, required storage, and supported device models. Keeping your operating system updated can also improve performance, security, and access to the newest application features.
04Does Avant require an account or personal information?
Avant may require users to create an account or provide information in order to access certain functions, save progress, personalize the experience, or use connected services. The information requested can vary depending on the app’s purpose and region. Before registering, read its privacy policy and permissions carefully so you understand how your data may be collected, stored, and used.
05Is Avant safe to download and use?
The safest way to install Avant is through its official Google Play Store or Apple App Store listing, rather than from unknown websites or modified files. Before downloading, verify the developer name, recent updates, user reviews, requested permissions, and privacy information. No application is completely risk-free, so avoid sharing unnecessary sensitive data and keep the app updated.


